
The view before the September 23 open
This market view was prepared at 08:00 EDT on September 23, 2026. Equity prices are September 22 regular-session closes; yields are that day's Treasury par yields. Premarket context comes from Yahoo Finance's 04:05 EDT report, with Brent prices reported by Reuters as of 02:51 EDT. September 23 regular-session results are not included. Passages labeled GSDAQ's interpretation distinguish our reading of the evidence from reported facts. This dated article does not update automatically.
Sources: MarketEdge · September 22, 2026 market close · U.S. Treasury · September 2026 daily par yield curve · Reuters · Oil falls on better supply outlook (September 23, 06:51 GMT prices) · Yahoo Finance · September 23 premarket (04:05 EDT)
Another record, different directions
The Nasdaq closed at a record 27,244.28. The S&P 500 slipped just 0.06 points and the Dow fell 0.36%. Semiconductors gained 2.06%, while the Russell 2000 rose 0.51%. GSDAQ's interpretation: this was neither a rally confined entirely to big technology companies nor a market advancing uniformly. A record index and a mixed experience across individual holdings can coexist.
Sources: MarketEdge · September 22, 2026 market close
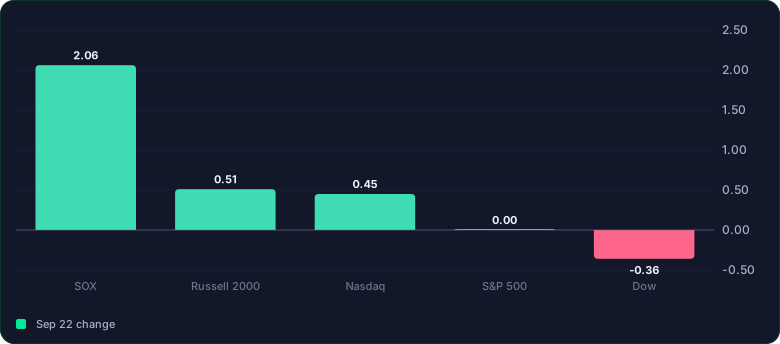
Read the chart as a table
| Sep 22 change (%) | |
|---|---|
| SOX | 2.06 |
| Russell 2000 | 0.51 |
| Nasdaq | 0.45 |
| S&P 500 | 0.00 |
| Dow | -0.36 |
On narrow screens, scroll the table sideways. Keyboard users can focus the table and use the arrow keys.
Meta paused while chips advanced
Meta closed at $736.60, down 0.63%, following Monday's 11.43% jump. One down day is too little evidence to call the end of AI enthusiasm. The semiconductor gain alongside it shows that an application provider's stock and expectations for computing infrastructure need not move together every day. GSDAQ's interpretation: separate three questions—how much people use AI, whether that use produces recurring revenue, and whether cash remains after the cost of serving it. A rising stock price does not settle those questions.
Sources: MarketEdge · September 22, 2026 market close · Stock Analysis · Meta daily price history (September 21–22)
Below 5%, but only by four basis points
The Treasury's September 22 ten-year par yield was 4.96%, unchanged from Monday. The two-year yield declined five basis points to 4.71%; the thirty-year stayed at 5.29%. GSDAQ's interpretation: Monday's decline in longer yields should not be described as another decline on Tuesday. The ten-year remains just four basis points below 5%. Optimism about AI investment and earnings does not, by itself, establish a substantial easing in financing costs.
Sources: U.S. Treasury · September 2026 daily par yield curve
On narrow screens, scroll the table sideways. Keyboard users can focus the table and use the arrow keys.
Cheaper oil, diplomacy still to deliver
Brent futures traded at $98.47 a barrel at 02:51 EDT on September 23, down 0.79% from the prior settlement. Reuters linked the decline to improved supply prospects following the restart of Saudi Arabia's East-West pipeline and hopes for US–Iran talks. By Yahoo Finance's 04:05 EDT report, major US equity futures were broadly flat. GSDAQ's interpretation: lower oil can ease cost pressures, but hopes for negotiations and implementation of an agreement are separate stages. Watch whether shipping and supply actually recover. These prices belong to their stated observation times.
Sources: Reuters · Oil falls on better supply outlook (September 23, 06:51 GMT prices) · Yahoo Finance · September 23 premarket (04:05 EDT)
What would validate a new story?
In the September 21 article, I saw GPU-backed financing and GPT-6 Astra as the beginning of a new story. The next questions should be concrete. Does AI demand turn announcements and downloads into recurring revenue? Does infrastructure investment leave enough cash to meet interest and operating costs? Does market participation broaden across companies and sectors? These are conditions to assess, not newly established results. The scale of a technological change and whether current stock prices value it appropriately also require separate judgments.
Sources: GSDAQ · September 21 market view
Three things to follow after the open
Wednesday's scheduled S&P activity data and company earnings offer further evidence on demand and costs. This week's US–China meetings could also turn discussions about AI and trade into concrete announcements. After the open, the useful comparison is among market participation, oil and Treasury yields, and evidence in AI-related company results. A record alone does not predict the next move. The question is whether the evidence continues to support the new-story view introduced in the previous article.
Sources: Yahoo Finance · September 23 premarket (04:05 EDT) · GSDAQ · September 21 market view
Sources
- MarketEdge · September 22, 2026 market close
- Stock Analysis · Meta daily price history (September 21–22)
- U.S. Treasury · September 2026 daily par yield curve
- Reuters · Oil falls on better supply outlook (September 23, 06:51 GMT prices)
- Yahoo Finance · September 23 premarket (04:05 EDT)
- GSDAQ · September 21 market view