
The September 24 cutoff
This report uses information checked through 9:45 p.m. EDT on September 24, 2026. Equities use regular-session closes; Treasury rates use that day’s official par yields; oil uses November-contract settlements. Treasury par yields are derived from indicative quotes around 3:30 p.m., so they differ from intraday highs and live 4 p.m. quotations. After-hours equity trading is excluded. This article does not update automatically.
Sources: MT Newswires · September 24 US market close (17:07 EDT) · U.S. Treasury · September 2026 daily par yield curve · Reuters · September 24 oil settlements · Dow Jones · November Brent and WTI, September 24 settlements
Flat indexes, more declining stocks
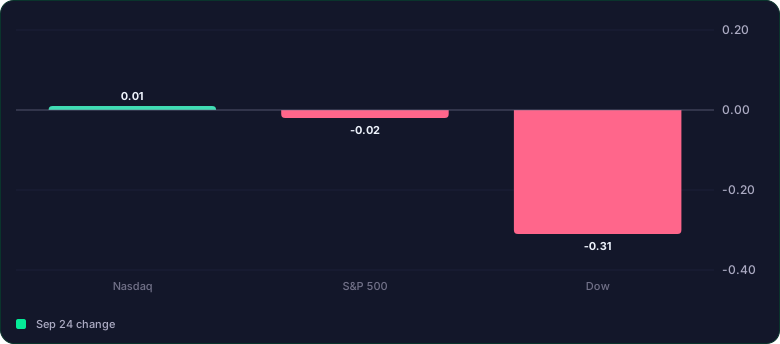
The Nasdaq closed at 26,939.37 and the S&P 500 at 7,704.13, changing just +0.01% and −0.02%. The Dow fell another 0.31%. NYSE decliners outnumbered advancers 1,769 to 961; Nasdaq exchange figures were 1,914 to 1,474. GSDAQ’s reading: stable headline indexes do not yet demonstrate a broad recovery. Exchange-wide stock counts and capitalization-weighted indexes measure different things.
Sources: MT Newswires · September 24 US market close (17:07 EDT) · Investing.com · September 24 exchange breadth and closing changes
Read the chart as a table
| Sep 24 change (%) | |
|---|---|
| Nasdaq | 0.01 |
| S&P 500 | -0.02 |
| Dow | -0.31 |
On narrow screens, scroll the table sideways. Keyboard users can focus the table and use the arrow keys.
Ten-year at 5.18%, up 22bp in two sessions
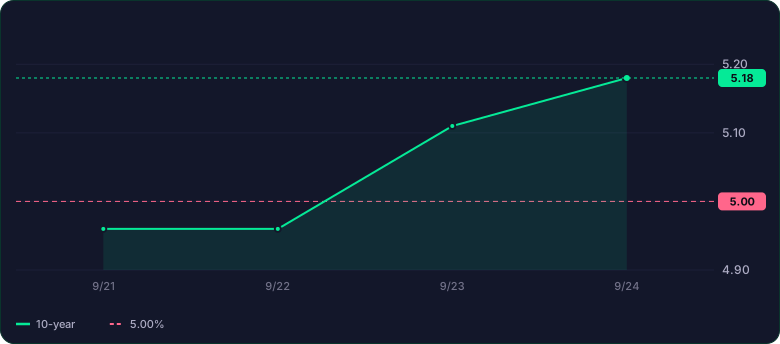
The Treasury’s 10-year par yield rose another 7bp, from 5.11% to 5.18%. Against September 22’s 4.96%, that is a 22bp increase over two sessions. The 30-year rose 7bp to 5.47%; the two-year added 2bp to 4.87%. GSDAQ’s reading: longer maturities moved more today, raising the cost benchmark for long-term investment. The whole move cannot be attributed to expectations for the next Fed meeting alone.
Sources: U.S. Treasury · September 2026 daily par yield curve
Read the chart as a table
| 10-year (%) | |
|---|---|
| 9/21 | 4.96 |
| 9/22 | 4.96 |
| 9/23 | 5.11 |
| 9/24 | 5.18 |
On narrow screens, scroll the table sideways. Keyboard users can focus the table and use the arrow keys.
Oil rose while talks remained unresolved
November Brent settled at $106.60 a barrel and November WTI at $94.61, up about 3.4% and 2.7%. Reuters linked supply concerns to a Houthi missile attack on Saudi Arabia. Oil later retreated from session highs after reports of US-Iran discussions about reopening the Strait of Hormuz. Discussions do not mean the route has reopened. GSDAQ’s reading: negotiation hopes in equity prices need to be checked alongside the energy costs businesses still face.
Sources: Reuters · September 24 oil settlements · Dow Jones · November Brent and WTI, September 24 settlements
On narrow screens, scroll the table sideways. Keyboard users can focus the table and use the arrow keys.
Meta +4.50%, Microsoft −0.53%
Large technology stocks also diverged: Meta gained 4.50%, while Microsoft fell 0.53%. Reuters highlighted Meta’s unveiling of a small device for its AI assistant as a backdrop to the gain. GSDAQ’s reading: a product announcement can improve expectations for one company. One day’s price response is insufficient evidence of better profitability across the AI industry. Usage, paid revenue and costs still need to be checked.
Sources: Reuters · September 24 close, Middle East negotiations and Meta
The cost a new narrative must carry
In the September 21 article, June described changes in AI and GPU financing as a new market narrative. Today’s figures cannot settle whether that view will prove right. They do show that the story is developing alongside higher financing and energy costs. GSDAQ’s reading: evidence of new demand and evidence that it generates enough cash are separate tests. As products arrive, the questions become concrete: when does revenue arrive, what cash remains after investment, and on what terms is expansion financed?
Three checks for the next session
First, watch whether the 10-year yield retreats and how equities respond. Second, check whether more stocks advance on both the NYSE and Nasdaq exchanges. Third, look for actual shipping and supply recovery after Hormuz announcements. Improvement across all three would provide more support for reading today’s flat close as the start of a recovery. If indexes hold while yields, oil costs and declining-stock counts remain elevated, participation would still look narrow. These are observation criteria, not trading signals.
Sources
- MT Newswires · September 24 US market close (17:07 EDT)
- U.S. Treasury · September 2026 daily par yield curve
- Reuters · September 24 close, Middle East negotiations and Meta
- Reuters · September 24 oil settlements
- Dow Jones · November Brent and WTI, September 24 settlements
- Investing.com · September 24 exchange breadth and closing changes
- GSDAQ · September 21: a new market narrative