The October 7 close in brief
All four major indexes fell in the October 7 regular session, and the Russell 2000 posted the largest decline at -1.3%. The 10-year Treasury note auctioned that day drew a high yield of 5.300% and a bid-to-cover ratio of 2.77. The September FOMC minutes, released in the afternoon, showed for the first time that most participants judged at the meeting that a further rate increase by year-end would likely be appropriate. However, the data obtained for this brief cannot separate the effects of the two events on yields or stock prices. This brief reflects information as of 4:00 p.m. PDT on October 7. Regular-session closes are as of 4:00 p.m. EDT (1:00 p.m. PDT) on October 7. It was a normal trading day with no early close.
Sources: NYSE trading hours information
Index closes: Same direction, with a steeper drop for small caps
Percentage changes are AP's rounded figures. Yesterday the S&P 500 rose while the Russell 2000 fell. Today both indexes declined. The Russell 2000 fell more than the S&P 500. Moving in the same direction does not mean the size of the declines, or how broadly stocks fell, was the same. After-hours prices are not included.
Sources: AP final market close tally
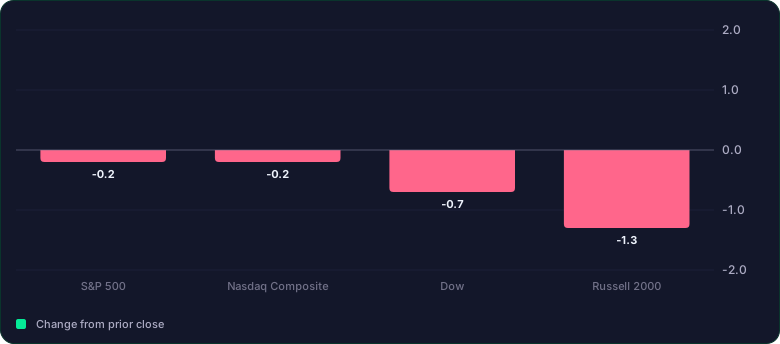
Read the chart as a table
| Change from prior close (%) | |
|---|---|
| S&P 500 | -0.2 |
| Nasdaq Composite | -0.2 |
| Dow | -0.7 |
| Russell 2000 | -1.3 |
On narrow screens, scroll the table sideways. Keyboard users can focus the table and use the arrow keys.
10-year auction: Confirmed figures and an unconfirmed reaction
In its October 7 auction, the Treasury reopened an existing 10-year note with 9 years and 10 months remaining to maturity, offering $39 billion. The figures below are from the official results announcement and match the values in the Treasury's API. · High yield of 5.300%: the highest yield accepted in this auction. · Bid-to-cover ratio of 2.77: the amount bid divided by the amount accepted. Both amounts exclude SOMA. It does not indicate the number of institutions that bid. · Indirect bidders' share of allotments, 80.3%: the share of total competitive accepted amounts allotted to the indirect bidder category, calculated by GSDAQ. These figures show the dollar amount of demand in this auction and how allotments were divided by category. They do not identify individual investors, and indirect bidders cannot all be assumed to be foreign buyers or central banks. Because no comparison with past auctions was made, this brief does not judge whether demand was stronger than usual, and these figures are not used to say anything about a peak in yields or future yield declines. The timing also needs to be kept distinct. 1:00 p.m. EDT (10:00 a.m. PDT) was the deadline for competitive bids. The exact time the results were first made public was not confirmed. The official release shows only the date, and the API's update timestamp does not establish when the results were first published. A 10-year yield time series from just before and just after the auction was also not obtained, so this brief does not address how many basis points the auction results moved yields. AP reported that the 10-year yield touched 5.36% at one point in the morning and later eased to 5.28%. The article does not give the time of each observation, and neither is an official close, so this move is not attributed to the auction or the minutes.
Sources: U.S. Treasury auction results announcement · TreasuryDirect auction data API · AP report
September minutes: What could be read for the first time today
The Fed released the minutes of its September 15–16 meeting at 2:00 p.m. EDT (11:00 a.m. PDT) on October 7. The Committee's decision at that meeting to raise the target range by 0.25 percentage point to 3.75–4.00% was already known, and the vote was 12–0. What the minutes newly showed was participants' views on the path ahead. Most participants judged that one more increase in the target range by year-end would likely be appropriate. In the same paragraph, participants emphasized that they would approach each meeting with an open mind and that future decisions would depend on incoming information and its implications for the outlook and the balance of risks. This view reflects participants' discussion based on information available at the time of the September meeting. It is not a new rate decision by the Committee or its position as of October 7. At the September meeting, all participants supported the 0.25 percentage point increase in the target range. Where they differed was on the rationale, discussed at the September meeting, for a higher path for the target range. Many participants saw a higher path as prudent from a risk-management standpoint: insurance against the risk that inflation would stay above target because of stronger-than-expected demand or additional supply shocks. A number of participants saw a higher path as necessary based on their baseline economic outlook rather than on risk management. Almost all participants pointed to upside risks to inflation and judged that labor market risks had diminished and were roughly balanced. The next policy meeting is October 27–28.
Sources: Federal Reserve FOMC minutes · Federal Reserve monetary policy press release · Federal Reserve monetary policy press release · decision · Federal Reserve monthly calendar
Answers to the morning's questions and remaining limits
The auction figures record the dollar demand and allotment breakdown for a single auction on October 7, while the minutes record how participants viewed the policy rate at the time of the September meeting. One does not answer the question posed by the other. What can be confirmed one hour apart are the 1:00 p.m. EDT competitive bid deadline and the 2:00 p.m. EDT release of the minutes. Because the time the auction results were first published and a before-and-after time series for the same instrument were not confirmed, the effects of the two events on yields or stock prices cannot be separated. Nor does this brief link the two events to conclude that they caused the decline at the close. August consumer credit, also listed on the calendar, was released at 3:00 p.m. EDT (12:00 p.m. PDT). On a preliminary basis, total consumer credit rose at an annual rate of +1.9% in August, a slower pace than July's revised annual rate of 4.1%. By type, revolving credit changed at an annual rate of -4.2% and nonrevolving credit at an annual rate of +4.1%. All are seasonally adjusted monthly changes expressed at annual rates; they do not directly measure consumer spending or delinquencies. They are also not treated as a cause of today's decline at the close. The three items this morning's brief said it would watch are summarized below.
Sources: Federal Reserve G.19 Consumer Credit
On narrow screens, scroll the table sideways. Keyboard users can focus the table and use the arrow keys.
| Morning question | Answer confirmed at the close | Remaining limits |
|---|---|---|
| Demand at the 10-year auction and yields before and after the release | Bid-to-cover ratio and allotment breakdown by category confirmed | Time results were first published and minute-by-minute yield reaction not confirmed |
| What the minutes added beyond the September statement | Most participants' view of another hike by year-end, a data-dependent approach, and differing reasons for raising rates | Views as of September, not a new decision. Verification of price effects on hold |
| Diverging direction of the S&P 500 and Russell 2000 | Both fell today, with a larger decline in the Russell 2000 | How broadly stocks fell cannot be determined from these figures |
About this brief
GSDAQ wrote and reviewed this brief from public sources with the help of AI tools. It is for information only and is not a recommendation to buy or sell any security or investment advice.
Sources
- NYSE trading hours information
- AP final market close tally
- U.S. Treasury auction results announcement
- TreasuryDirect auction data API
- AP report
- Federal Reserve FOMC minutes
- Federal Reserve monetary policy press release
- Federal Reserve monetary policy press release · decision
- Federal Reserve monthly calendar
- Federal Reserve G.19 Consumer Credit